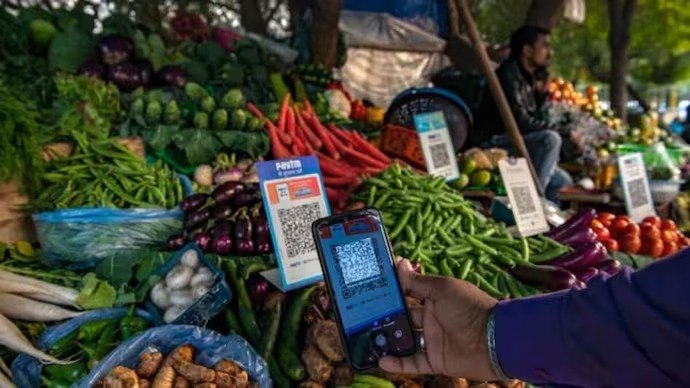
India’s Unified Payments Interface (UPI) completes multi-stage digital transactions in under five seconds through a synchronized four-step relay between banks, payment switches, and mobile networks.
The Four-Stage Digital Relay
Behind every instant payment notification lies a disciplined electronic pathway. When a user inputs a passcode to authorize a transfer, the smartphone encapsulates the request into an encrypted text file spanning a few hundred bytes. This data packet travels over dedicated fiber optic cables to the National Payments Corporation of India (NPCI), which operates as the central switchboard for nationwide financial routing.
NPCI evaluates the destination details and forwards a debit request to the payer’s financial institution, known as the remitter bank. The remitter bank verifies the user’s identity and checks for adequate account funds. Upon verification, the bank reserves the specified balance and transmits an approval code back to the central NPCI switchboard.
Ledger Synchronization and Settlement
Instead of physically transmitting currency across digital networks, the architecture relies on synchronized balance adjustments. Upon receiving approval from the remitter bank, NPCI instructs the merchant’s beneficiary bank to credit the recipient’s account. The beneficiary bank validates the destination account, updates its internal ledger, and sends a final confirmation back through the chain.
Paytm par pachaas rupaye praapt huye. Paytm karo
Once the confirmation cycle completes between the banks and NPCI, a final signal travels over cellular networks to trigger the merchant’s soundbox or mobile device. While customer balances update immediately during the transaction, the actual transfer of money between the institutions takes place later through official settlement accounts maintained at the Reserve Bank of India.
System Architecture and Capacity Limits
The speed of the system relies on sending minimal data payloads across direct fiber optic lines connecting banking data centers. However, infrastructure constraints can occasionally interrupt this mechanism. During end-of-year financial accounting in March, high traffic volume raised processing loads on address lookup systems beyond 95 percent. The resulting delay increased processing times from 50 milliseconds to over two seconds, causing approximately 7,000 transactions per second, valued at nearly Rs 1 crore, to temporarily stall across the country.
TL;DR
- UPI payments complete through a four-part system in under five seconds.
- Encrypted data packets travel via fiber optics to central NPCI switches.
- Remitter banks verify user identity and account balance within milliseconds.
- Banks update internal balances instantly while RBI settles funds later.
- High system loads can stall up to 7,000 transactions per second nationwide.